
75-15-10 Budgeting Calculator
Includes: Rent/Mortgage, Utilities, Groceries, Transport, Insurance, Minimum Debt Payments.
Includes: Emergency Fund, Retirement/Super, Investments, Extra Debt Repayment.
Includes: Hobbies, Dining Out, Gifts, Travel, Entertainment, Impulse Buys.
You stare at your bank balance on payday. It’s a familiar ritual for most of us. The money hits the account, and within seconds, you know exactly where it’s going: rent, bills, groceries, that subscription you forgot to cancel. By the time the month ends, you’re left wondering where the rest went. Did you actually save anything? Or did you just survive?
Most people fail at budgeting not because they lack discipline, but because their plans are too rigid or too vague. You either track every single coffee (which drives you crazy) or you don’t track anything (which leaves you broke). There is a middle ground, though. It’s called the 75-15-10 rule. This isn’t some complex algorithm from Wall Street. It’s a straightforward framework designed to simplify how you allocate your income. It cuts through the noise by giving you three clear buckets. No spreadsheets required. Just percentages.
The Core Concept: Breaking Down the Buckets
At its heart, this method divides your net income-what actually lands in your bank account after tax-into three distinct categories. Think of it as a traffic light system for your cash flow. Each percentage has a specific job, and mixing them up causes jams.
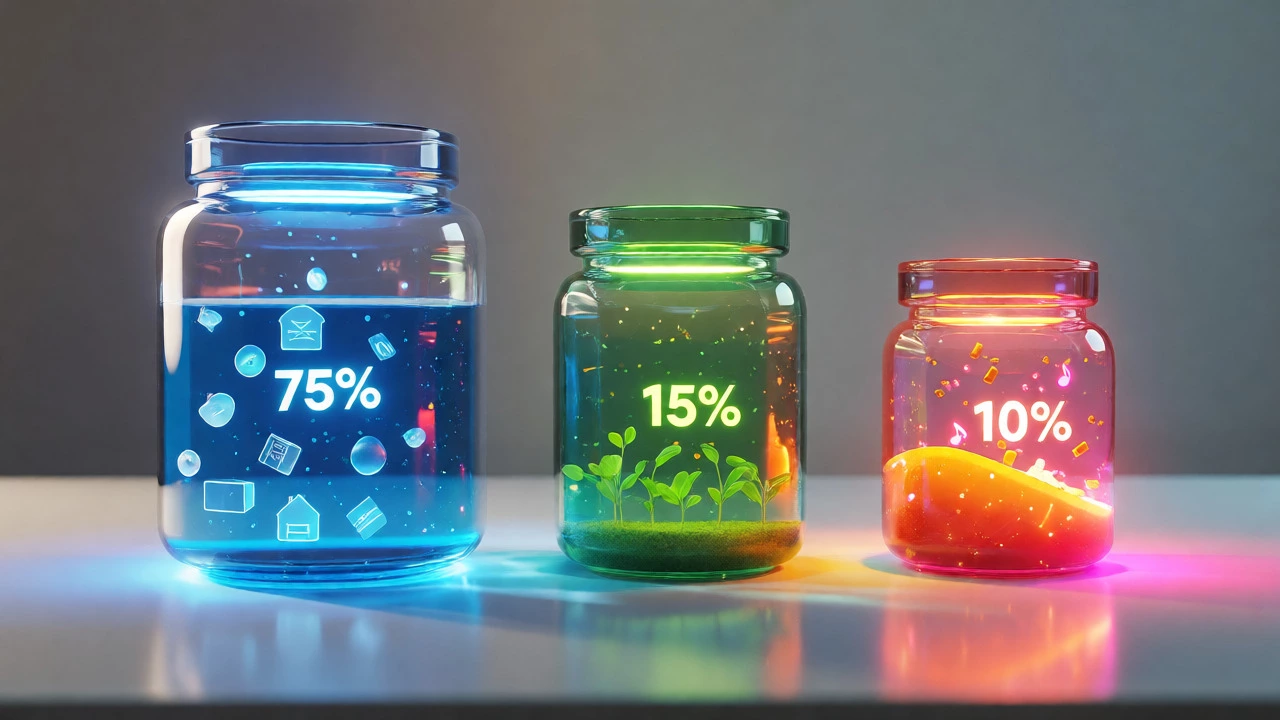
| Percentage | Category | Purpose | Examples |
|---|---|---|---|
| 75% | Essential & Daily Living | Covering needs and basic wants | Rent/mortgage, utilities, food, transport, insurance, minimum debt payments |
| 15% | Financial Goals | Building wealth and security | Emergency fund, retirement contributions, investment accounts, extra debt repayment |
| 10% | Guilt-Free Spending | Enjoyment without regret | Hobbies, dining out, gifts, travel, entertainment, impulse buys |
Why these numbers? They aren’t random. The 75% bucket is generous enough to cover actual living costs in high-cost cities like Sydney, where housing eats up a massive chunk of income. The 15% ensures you’re paying your future self before you spend on yourself. And the 10%? That’s your sanity saver. It prevents the burnout that comes with strict austerity budgets.
Step One: Mastering the 75% Essential Bucket
This is the largest slice of the pie, but it’s also the most dangerous if you let it creep. For many Australians, especially those renting in major metros, housing alone can consume 40% or more of net income. If your rent or mortgage is pushing your total essentials over 75%, you have a problem. You’re likely dipping into your savings or spending money to keep the lights on.
Here’s what belongs in this category:
- Housing: Rent, mortgage repayments, strata fees, or council rates.
- Utilities: Electricity, gas, water, internet, and mobile phone plans.
- Food: Groceries and basic household supplies. Note: Dining out usually falls under the 10% guilt-free bucket, unless it’s a work necessity.
- Transport: Public transport fares, fuel, car registration, and insurance.
- Healthcare: Health insurance premiums and out-of-pocket medical costs.
- Minimum Debt Payments: The mandatory minimums on credit cards or loans. Any payment above the minimum goes to the 15% goal bucket.
A common mistake here is including "wants" disguised as needs. Do you really need the $80/month streaming bundle? Probably not. But do you need reliable internet to work from home? Yes. Scrutinize this bucket monthly. If you find yourself constantly overspending here, you might need to renegotiate bills, switch providers, or consider moving to a more affordable area. In Sydney, for example, sharing accommodation can instantly free up 10-15% of your income, shifting the balance back in your favor.
Step Two: Automating the 15% Financial Goals
This is where wealth is built. Most people treat savings as whatever is left over at the end of the month. Spoiler alert: there’s rarely anything left. The 75-15-10 rule flips this script. You pay yourself first. Before you buy a new pair of shoes, you move 15% of your paycheck into financial goals.
But "financial goals" is broad. How do you split this 15%? It depends on your life stage.
If You Have High-Interest Debt
Prioritize killing debt. Credit card interest rates in Australia often hover around 15-20%. Paying off a $5,000 balance saves you thousands in interest. Direct most of this 15% toward extra debt payments until you’re clear. Once the debt is gone, redirect that entire 15% to investments.
If You’re Building an Emergency Fund
Life happens. Cars break down. Jobs get lost. An emergency fund covers 3-6 months of essential expenses. Until you hit that target, keep this money in a high-interest savings account. It’s not for investing; it’s for safety. Aim to build this fund before aggressively investing in volatile markets.
If You’re Ready to Invest
Once your emergency fund is solid and high-interest debt is gone, this 15% becomes your engine for growth. Contribute to your superannuation (if you’re in Australia), open an ETF portfolio, or put money into index funds. The power here is consistency. Investing $500 a month for 30 years yields vastly different results than trying to time the market with lump sums.
Superannuation plays a huge role here. Your employer already contributes 11% (as of 2024-2025 rates) into your super. Does that count towards your 15%? Technically, yes, but many experts recommend aiming for a total contribution rate of 15-20% of gross income. If your employer only pays the minimum, you should top up the difference voluntarily to ensure you’re on track for a comfortable retirement.
Step Three: Enjoying the 10% Guilt-Free Zone
This is my favorite part of the rule. Traditional budgets feel like punishment. You cut out lattes, skip happy hours, and eat rice and beans. Then, one Friday night, you blow the whole budget on a fancy dinner because you’re starving for joy. The 10% bucket eliminates that cycle.
This money is yours to spend however you want. Buy the expensive wine. Book the weekend trip. Upgrade your headphones. Don’t track it. Don’t justify it. Just spend it. When you know you have $300 set aside specifically for fun, you stop feeling guilty when you use it. You also stop raiding your grocery budget for treats because you have a dedicated pot for extras.
Psychologically, this small allowance makes the other 90% sustainable. Humans aren’t robots. We need rewards. Without them, discipline collapses. The 10% acts as a pressure valve, releasing stress so your long-term financial health doesn’t suffer.
Real-World Application: A Sydney Salary Example
Let’s make this concrete. Imagine Sarah, a marketing coordinator in Sydney earning $75,000 a year. After tax and Medicare levy, her net monthly income is roughly $4,800.
- 75% Essentials ($3,600): She rents a share house for $1,200. Utilities and internet cost $250. Groceries are $600. Transport is $200. Phone and subscriptions are $100. Minimum loan payments are $150. That totals $2,500. She has $1,100 left in this bucket for unexpected costs or slightly higher rent later.
- 15% Goals ($720): She automates $400 into her emergency fund and $320 into a low-cost index fund. She doesn’t touch this money manually. It disappears from her checking account the day she gets paid.
- 10% Fun ($480): This is her play money. She spends $200 on brunches, $100 on clothes, and saves the rest for a concert ticket. If she spends it all by week two, she waits until next month. No borrowing from savings allowed.
Sarah isn’t stressed about tracking every cent. She knows her boundaries. Her essentials are covered, her future is funded, and she’s still living a social life. That’s the power of structure.
Common Pitfalls and How to Avoid Them
Even simple rules get messed up. Here’s where people typically go wrong with the 75-15-10 method.
Ignoring Irregular Expenses
Car registrations, birthday gifts, and holiday travel don’t happen every month. If you ignore them, you’ll dip into your 10% or 15% buckets unexpectedly. Solution: Create a "sinking fund" within your 75% bucket. Estimate annual irregular costs, divide by 12, and save that amount monthly in a separate sub-account.
Underestimating Lifestyle Creep
When you get a raise, your spending tends to rise to meet it. If your income jumps, don’t just increase your 75% bucket. Increase your 15% and 10% proportionally. Otherwise, you’re working harder for no extra freedom.
Treating Savings as Variable
Some months, you might think, "I’ll skip savings this month." Don’t. Automation is key. Set up automatic transfers to your savings and investment accounts immediately after payday. If the money isn’t in your checking account, you won’t miss it as much.
Is the 75-15-10 Rule Right for You?
No budgeting method fits everyone perfectly. This rule works best for salaried employees with stable income who struggle with overspending or lack a clear plan. It’s forgiving enough for beginners but structured enough for serious savers.
However, if your housing costs exceed 50% of your income, the 75% bucket will be tight. You might need to adjust the ratios temporarily-perhaps 80-10-10-until you can reduce fixed costs. Conversely, if you’re extremely frugal or aiming for early retirement (FIRE), you might push savings to 20-30% and trim essentials to 60%.
Start with the standard 75-15-10. Track it for three months. See where you naturally deviate. Adjust the percentages to fit your reality, not someone else’s ideal. The best budget is the one you can stick to.
Does the 75-15-10 rule apply to gross or net income?
It applies to net income, which is the take-home pay after taxes and deductions. Using gross income can lead to overestimating your available funds, causing you to fall short on essentials since taxes are mandatory.
What if my rent is higher than 75% of my income?
If your fixed costs are too high, the standard ratio may not work. Consider adjusting to an 80-10-10 split temporarily. Focus on increasing income or reducing housing costs (e.g., getting a roommate) to eventually return to a healthier balance.
Can I combine the 15% and 10% buckets?
You can, but it’s risky. Combining them blurs the line between responsible saving and discretionary spending. Keeping them separate creates psychological barriers that protect your long-term wealth from short-term desires.
How does this compare to the 50/30/20 rule?
The 50/30/20 rule allocates 50% to needs, 30% to wants, and 20% to savings. The 75-15-10 is more conservative on spending (only 10% for wants) and less aggressive on savings (15%). It’s better suited for those in high-cost-of-living areas where needs consume more than 50% of income.
Do I need to track every purchase?
No. The beauty of this rule is automation. If you set up automatic transfers for the 15% and monitor your 75% essentials broadly, you only need to glance at your 10% spending occasionally. It reduces mental load significantly compared to zero-based budgeting.