
Equity Release Estimator & Comparison Tool
Use this tool to estimate how much cash you could unlock from your home and understand the trade-offs between retaining ownership and minimizing debt growth.
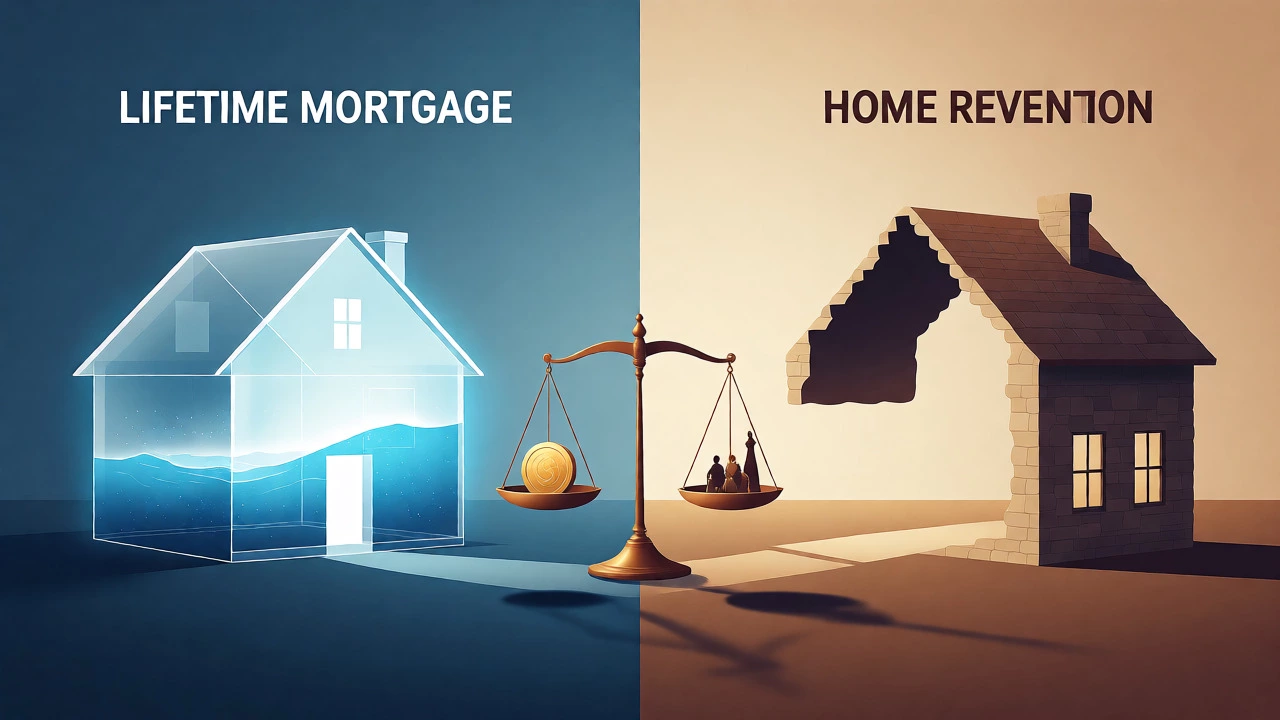
Lifetime Mortgage
Keep 100% Ownership | Interest Compounds
Home Reversion
Sell Share of Property | No Debt Growth
Enter your details to see a comparison of equity release options.
Imagine you own a beautiful home worth $800,000, but your bank account says you can barely afford groceries. This is the classic "asset rich, cash poor" dilemma that traps many retirees. You have wealth locked in your walls, but it doesn't pay for your holidays or medical bills. Equity release is the financial tool designed to unlock this value, allowing you to access the money tied up in your property while continuing to live there. But with so many options on the market, how do you know which path is right for you?
Understanding the Core Mechanism
Before comparing products, you need to understand what you are actually selling or borrowing against. Equity release isn't one single product; it's an umbrella term for two main types of agreements: lifetime mortgages and home reversion plans. Choosing the wrong one can cost you tens of thousands of dollars in lost inheritance or higher interest costs down the track.
A lifetime mortgage is essentially a loan secured against your home. Unlike a standard mortgage where you make monthly repayments, here the interest rolls up (compounds) into the loan balance. You typically don't pay anything back until you die, move into long-term care, or sell the house. The big advantage? You retain full ownership. If property prices skyrocket, you still own 100% of the asset appreciation.
In contrast, a home reversion plan involves selling all or part of your home to a provider in exchange for a tax-free lump sum or regular income. You stay in the property rent-free for life. The catch? You lose ownership of the portion you sold. If you sell 50% of your home, you only own half of any future growth in its value. This option is less common today because it often results in a lower immediate payout compared to a lifetime mortgage.
Lifetime Mortgages: The Popular Choice
For most people asking "what is the best way," the answer usually points toward a lifetime mortgage. It’s flexible, widely available, and allows you to keep control of your estate. However, not all lifetime mortgages are created equal. You need to look at three specific features to determine if a deal is good.
First, check the No Negative Equity Guarantee. This is non-negotiable. It ensures that you will never owe more than the value of your home when it is eventually sold, even if interest rates spike and compound aggressively over 20 years. Without this guarantee, your debt could theoretically exceed your home’s value, eating into your estate completely.
Second, look for flexibility in withdrawals. Many modern providers offer "drawdown" facilities. Instead of taking a huge lump sum upfront and paying interest on all of it immediately, you take a small amount now and leave the rest untouched. You only pay interest on the money you actually use. This can save you significant interest over the life of the loan. For example, taking $50,000 now versus $200,000 now makes a massive difference in how fast the debt grows.
Third, consider partial repayment options. Life changes. Maybe you inherit some money or decide to downsize earlier than expected. Some contracts allow you to repay portions of the loan penalty-free within certain limits (often 10-20% per year). Others lock you in for 5-10 years with heavy exit fees. Always read the early repayment charges carefully.
Home Reversion: When Ownership Matters Less
Is a home reversion ever the best option? Yes, but only in specific scenarios. If you have a very high-value property but low income, and you absolutely want zero debt growing on your title, reversion might appeal. Since you are selling a share of the property, there is no interest rate to worry about. Your monthly outgoings remain exactly as they were, plus perhaps minor maintenance costs.
However, the trade-off is stark. Let’s say you sell 40% of your $1 million home. You get a lump sum now, but you’ve given away 40% of any future capital gains. If your home doubles in value to $2 million, you’ve effectively lost $400,000 in potential inheritance value compared to retaining full ownership. This makes home reversion a poor choice for those who prioritize leaving a substantial estate to their children.
Comparing the Options
To help you decide, here is a direct comparison of the two primary methods. Note that these figures are illustrative based on current Australian market trends for a typical retiree aged 70+.
| Feature | Lifetime Mortgage | Home Reversion |
|---|---|---|
| Ownership Retained | 100% | Reduced (based on % sold) |
| Debt Growth | Yes (Compound Interest) | No |
| Inheritance Impact | Reduces by loan + interest | Reduces by % of value sold |
| Flexibility | High (Drawdown options) | Low (Fixed sale price) |
| Best For | Those wanting to keep full ownership | Those wanting zero debt risk |
Factors That Determine the "Best" Deal
The "best" way isn't just about the lowest interest rate. It’s about alignment with your personal goals. Here are the critical factors you must weigh before signing anything.
Your Age: Younger retirees (65-70) have longer time horizons. Compound interest works against them harder. They should be extremely cautious with high-interest rates because 30 years of compounding can double or triple the debt. Older applicants (75+) might benefit from slightly higher rates if it means better drawdown flexibility, as the loan duration is shorter.
Health Status: Did you know that smoking or having certain health conditions can improve your equity release offer? Providers assess "life expectancy." If you are a smoker or have a serious illness, you are statistically likely to need the funds sooner and potentially leave the property later. This reduces the lender's risk, so they may offer you a larger lump sum or a lower interest rate. This is known as "enhanced equity release."
Property Location and Value: Lenders prefer stable markets. While Sydney and Melbourne properties are generally accepted, some lenders restrict lending in regional areas or for unusual property types (like apartments with low owner-occupancy ratios). Ensure your property meets the lender’s criteria before applying.
Costs Involved: Equity release isn't free. Expect setup costs including legal fees, valuation fees, and brokerage commissions. These can total several thousand dollars. Some providers cover these costs if you use their recommended solicitor, but always compare quotes independently.
The Process: How to Secure Your Funds
Getting equity release involves a structured process. Skipping steps can lead to bad advice or unsuitable products.
- Independent Advice: In Australia, independent financial advice is mandatory for equity release. You cannot just walk into a bank and sign. You must speak with a licensed advisor who specializes in retirement funding. They will assess your needs, family situation, and health.
- Product Selection: Based on the advice, you choose between a lifetime mortgage or reversion plan. The advisor compares offers from multiple lenders.
- Valuation: An independent valuer visits your home to determine its current market value. This figure dictates how much equity you can release.
- Legal Review: Your solicitor reviews the contract. They ensure the No Negative Equity Guarantee is present and explain the implications of interest roll-up.
- Fund Release: Once signed, the funds are transferred to your bank account. This can happen as a lump sum or in stages.
Pitfalls to Avoid
Many people regret their equity release decisions because they didn't anticipate the long-term effects. The biggest pitfall is underestimating compound interest. At a 5.5% interest rate, your debt doubles roughly every 13 years. If you take out $100,000 at age 70, it could be $200,000 by age 83, and $400,000 by age 96. This erosion of estate value surprises many families.
Another trap is ignoring impact on government benefits. In Australia, receiving a large lump sum can affect your eligibility for the Age Pension or other welfare payments due to assets tests. Speak to Centrelink or a financial planner to model this impact before withdrawing cash.
Finally, beware of pressure sales tactics. Some brokers push products that pay them higher commissions rather than what suits you. Always ask: "Why is this specific product better for me than Option B?" If they can't give a clear, personalized answer, walk away.
Does equity release affect my Age Pension?
Yes, it can. Equity release funds are generally treated as assets for the purposes of the assets test. If you take a large lump sum, it could temporarily reduce or eliminate your pension entitlement until the money is spent or invested. Regular drawdowns may have a smaller impact than a single large withdrawal. Always consult a financial advisor to calculate the precise effect on your specific situation.
Can I stay in my home after releasing equity?
Absolutely. Both lifetime mortgages and home reversion plans include a "right to live" clause. This guarantees you can remain in your property for the rest of your life, or until you move into permanent residential care, without paying rent. You are responsible for maintenance, insurance, and council rates, just as you would be if you owned the home outright.
What happens to the debt when I die?
When you pass away, the loan (plus accumulated interest) is repaid from the sale of your home. Any remaining proceeds go to your estate and beneficiaries. If the sale price is less than the debt owed, the No Negative Equity Guarantee protects your heirs from having to pay the shortfall out of pocket. The lender absorbs the loss.
Is equity release safe?
Equity release is regulated and safe when used correctly. The key safety net is the No Negative Equity Guarantee, which prevents owing more than the home is worth. Additionally, mandatory independent financial advice ensures you understand the risks. Problems usually arise when borrowers fail to maintain the property or ignore the compounding nature of the interest.
Can I change my mind after signing?
Most contracts have a cooling-off period, typically around 14 days, during which you can cancel without penalty. After that, exiting the agreement can be expensive due to early repayment charges. These charges vary by lender and product type, so review the terms carefully before signing. Some products allow partial repayments without penalty, offering more flexibility.