
Retirement Bucket Strategy Simulator
This tool helps you determine how to split your retirement savings into three buckets to balance growth potential with immediate security. Adjust the inputs below to see your recommended allocation.
Your Profile
Recommended Allocation
Enter your details and click Calculate to see your personalized bucket strategy.
You’ve worked hard for your money. You’ve paid off the house, maybe helped the grandkids with college, and now you’re sitting on a pile of savings that needs to last another decade or two. The question keeps popping up: should a 75 year old be in the stock market?
It’s not a simple yes or no. If you put everything in cash, inflation eats your purchasing power alive. If you keep it all in stocks, one bad Tuesday could ruin your sleep. The sweet spot exists, but it looks different for everyone. Let’s break down exactly how to think about this without the jargon.
The Real Risk Isn’t Just Losing Money
Most people think risk means watching a number go down on a screen. For a 75-year-old, risk is actually running out of money before you run out of life. This is called longevity risk. According to Social Security Administration data, a man who reaches age 65 has a roughly 20% chance of living to 90, and a woman has a nearly 30% chance. That’s a long time to fund from a portfolio.
If you are completely out of the stock market, holding only bonds and cash, you face a different danger: sequence of returns risk and inflation. Inflation doesn’t care about your age. If inflation averages 3% over the next 15 years, prices double. Your $500,000 nest egg buys what $250,000 buys today. Stocks have historically been the best tool to beat inflation, even if they are bumpy along the way.
Why Total Safety Can Be Dangerous
Let’s look at the math. Suppose you have $400,000 saved. You decide to play it safe and put it all in high-yield savings accounts and CDs (Certificates of Deposit). You might get 4% interest right now. Sounds nice, right? But taxes take a bite, and inflation takes another bite. If inflation is 3%, your real return is barely above zero.
Now, imagine you withdraw $20,000 a year to live on. With low growth, your principal starts shrinking every single year. By age 85, you might have half as much money left as when you started. Meanwhile, the cost of healthcare has likely skyrocketed. Being "safe" can actually make you poor in your later years because your money isn’t growing fast enough to keep up with life.
The Case for Keeping Some Stocks
So, why stay invested? Because stocks offer growth potential that bonds simply cannot match over long periods. Since 1926, the S&P 500 has returned an average of about 10% per year before inflation. Bonds have returned closer to 5%. That gap matters enormously when you need your money to last 20+ years.
But here is the catch: volatility. If you need to sell stocks during a crash, you lock in those losses. A 75-year-old usually has less time to wait for the market to bounce back than a 30-year-old. However, you don’t need to own individual tech stocks or meme coins. You need broad, diversified exposure.
Asset Allocation is the strategy of spreading your money across different types of investments to balance risk and reward. For a senior, this often means a mix of stocks for growth, bonds for income, and cash for immediate expenses.
A Practical Rule of Thumb: The Bucket Strategy
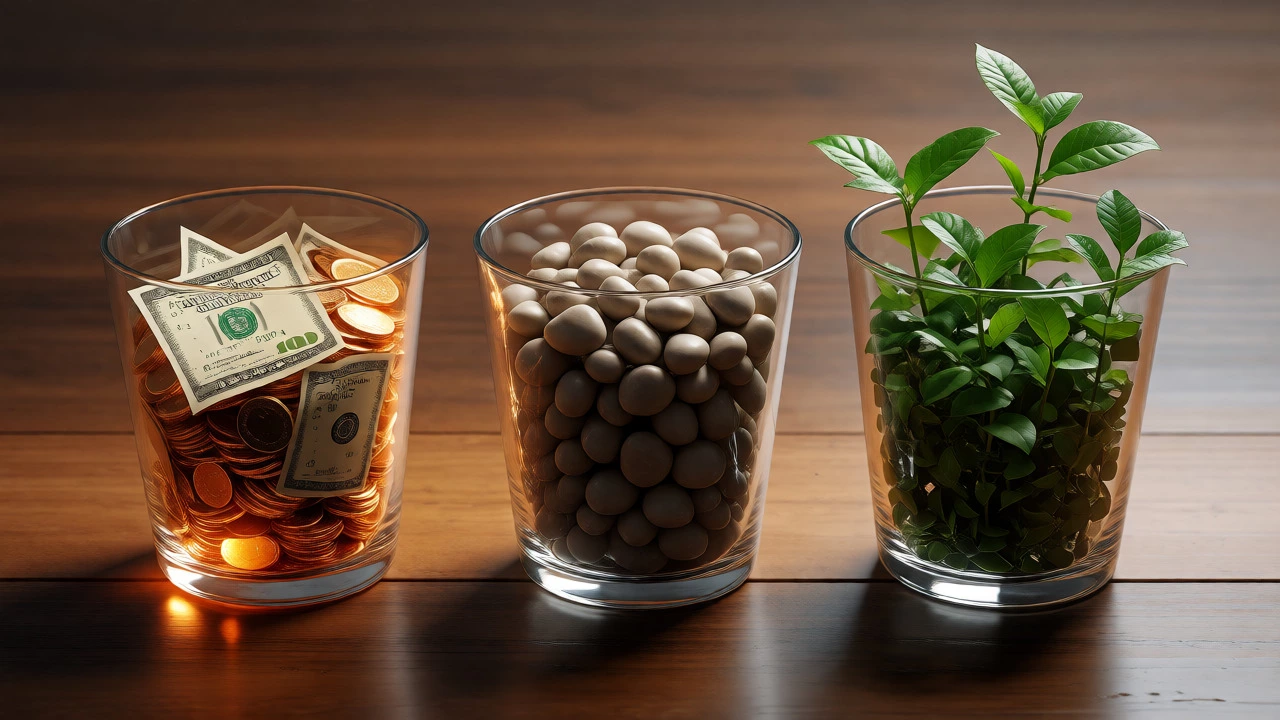
Instead of asking "how many percent in stocks," ask "when do I need this money?" The Bucket Strategy is a popular method among financial planners for retirees. It divides your assets into three buckets based on time horizon.
- Bucket 1: Immediate Cash (Years 1-2). Keep 1-2 years’ worth of living expenses in a high-yield savings account or money market fund. This money never touches the stock market. If the market crashes, you spend from this bucket and don’t have to sell stocks at a loss.
- Bucket 2: Short-Term Stability (Years 3-7). Put this money in short-term bonds, Treasury bills, or CDs. These are safer than stocks but pay more than cash. They protect your middle-term needs while earning some yield.
- Bucket 3: Long-Term Growth (Years 8+). This is where your stock market money lives. You won’t touch this money for at least 8 years. Because you have time, you can tolerate the ups and downs. Historically, this bucket grows the most, helping you combat inflation and leave a legacy.
This structure solves the psychological problem. When headlines scream "Market Crashes!" you know your next two years of groceries and rent are already secured in Bucket 1. You aren’t forced to panic-sell your stocks.
How Much Should You Actually Hold?
There is no magic number, but there are common guidelines. The old rule was "subtract your age from 110" to determine your stock percentage. For a 75-year-old, that would suggest 35% in stocks. Another popular formula is the "Rule of 100," which suggests subtracting your age from 100, leaving you with 25% in stocks.
However, these rules are blunt instruments. Your specific situation matters more:
| Scenario | Stocks (%) | Bonds/Cash (%) | Reasoning |
|---|---|---|---|
| Conservative / Health Issues | 10-20% | 80-90% | Prioritizes capital preservation; may have higher medical costs soon. |
| Moderate / Average Health | 30-40% | 60-70% | Balances growth against risk; suitable for most healthy retirees. |
| Aggressive / Legacy Focus | 50-60% | 40-50% | Planning to leave inheritance; has other income sources like pensions. |
If you have a guaranteed pension or substantial Social Security that covers your basic needs, you can afford to hold more stocks because your lifestyle doesn’t depend on selling shares during a downturn. If your entire income comes from withdrawals, you should lean toward the conservative side.
What About Individual Stocks vs. Funds?
Please, unless you are a seasoned investor, avoid picking individual stocks at 75. One company can fail, get sued, or become obsolete. Diversification is your friend. Broad-market index funds or Exchange-Traded Funds (ETFs) give you ownership in hundreds of companies at once. If one fails, you barely notice.
Consider dividend-paying stocks too. Companies like Johnson & Johnson or Procter & Gamble have paid dividends for decades. These provide regular cash flow without needing to sell shares. However, remember that dividends are not guaranteed, and the share price can still drop.
Common Mistakes Seniors Make
One major mistake is chasing yield. You see a bond paying 7% and buy it without checking why. Often, high yields mean high risk-maybe the company is struggling. Stick to investment-grade bonds or Treasury securities if safety is your priority.
Another error is ignoring tax implications. Withdrawals from traditional IRAs and 401(k)s are taxed as ordinary income. Selling stocks held for more than a year triggers lower capital gains rates. Working with a tax-aware advisor can save you thousands. Also, be wary of complex annuities sold by commission-based agents. They often come with high fees and surrender charges that lock up your money when you might need it for emergencies.
Final Thoughts: Balance Over Perfection
Should a 75-year-old be in the stock market? Yes, but carefully. Completely avoiding stocks exposes you to inflation risk. Fully embracing them exposes you to timing risk. The goal is resilience.
Review your portfolio annually. As you age, gradually shift profits from stocks into safer assets. Keep enough cash on hand so you never have to sell a good investment at a bad time. And talk to a fiduciary financial advisor-a fee-only planner who works for you, not a broker who earns commissions on what they sell you.
Your money should support your life, not stress you out. If your current allocation keeps you awake at night, adjust it. Peace of mind is worth more than an extra 1% return.
Is it too late to start investing in stocks at 75?
No, it is not too late. While you may not have 40 years for compound growth to work its magic, you likely have 10-20 years of life expectancy. Holding some stocks helps protect your purchasing power against inflation. The key is to limit the amount to what you won't need for at least 5-10 years, ensuring you aren't forced to sell during a market dip.
What is the safest investment for a 75-year-old?
For pure safety, U.S. Treasury Bills (T-Bills) and Series I Savings Bonds are considered among the safest options because they are backed by the full faith and credit of the U.S. government. High-yield savings accounts insured by the FDIC up to $250,000 are also very safe. However, "safest" does not always mean "best" for long-term wealth preservation due to inflation risks.
How much cash should a 75-year-old keep on hand?
A common recommendation is to keep 1 to 2 years' worth of essential living expenses in cash or cash equivalents (like money market funds). This creates a buffer that allows you to cover daily needs without selling other investments during market downturns. Additionally, maintaining an emergency fund of 3-6 months of expenses is prudent for unexpected medical or home repairs.
Does Medicare affect how I invest my retirement savings?
Yes, indirectly. Higher-income seniors pay Income-Related Monthly Adjustment Amounts (IRMAA) for Medicare Parts B and D. Large capital gains realizations or high withdrawal amounts can push you into a higher tax bracket, increasing your Medicare premiums. Strategic withdrawal planning and managing taxable income can help minimize these surcharges.
Are annuities better than the stock market for someone aged 75?
Annuities provide guaranteed income for life, which eliminates longevity risk, whereas the stock market offers growth potential but no guarantees. For some, a hybrid approach works well: using a portion of savings for an immediate annuity to cover basics, and keeping the rest in a diversified portfolio for flexibility and legacy goals. Annuities often have high fees and limited liquidity, so careful comparison is essential.