Home Equity Loan Eligibility Estimator
Enter your details below to see how much equity you can access and how lenders view your debt levels.
Assessment Summary
| DTI Range | Risk Level | Your Status |
|---|---|---|
| < 30% | Low | |
| 30% - 40% | Moderate | |
| 40% - 50% | High | |
| > 50% | Very High |
You own your home. Maybe you’ve paid off the mortgage years ago, or maybe you just have a chunk of value sitting there doing nothing but collecting dust. You need cash for renovations, a business venture, or to help family out. So, you walk into a bank expecting a simple transaction: "Here’s my house, give me some money against its value." Instead, you hit a wall. Rejections pile up. Interest rates look scary. The paperwork feels like applying for a second mortgage from scratch. Why is getting a home equity loan so difficult when the asset is right there in front of you?
The short answer: banks don’t lend against bricks and mortar; they lend against risk and repayment capacity. While your property provides security, the lender cares more about whether you can service the new debt without falling behind. In 2026, with economic volatility still lingering and interest rate cycles unpredictable, lenders have tightened their belts significantly. They aren't just looking at how much your house is worth; they are scrutinizing your entire financial life with forensic precision.
Your Credit Score Is the Gatekeeper
Think of your credit report as your financial reputation card. If you missed a payment three years ago, it might seem ancient history to you. To a lender, it’s a red flag. Home equity loans are secured debts, yes, but they are also long-term commitments. Lenders want to see a pattern of reliability.
Most Australian lenders use a credit score threshold that sits higher than what you might expect for a standard personal loan. Why? Because if you default on a home equity loan, the process of seizing and selling your home is expensive and time-consuming for them. They prefer borrowers who won’t force them down that road.
- Score Thresholds: A score below 600 (on many scoring models) often triggers automatic declines or requires a guarantor.
- Recent Inquiries: Too many recent credit applications signal desperation or over-leverage.
- Paid Defaults: Even if you paid off a default two years ago, it remains visible and impacts your trust rating.
If your credit file isn’t spotless, you’re not necessarily out of the game, but you will pay for it. Expect higher interest rates or lower Loan-to-Value Ratios (LVR). Some niche lenders specialize in "bad credit" equity releases, but their fees can eat up a significant portion of your borrowed capital upfront.
The Debt-to-Income Ratio Trap
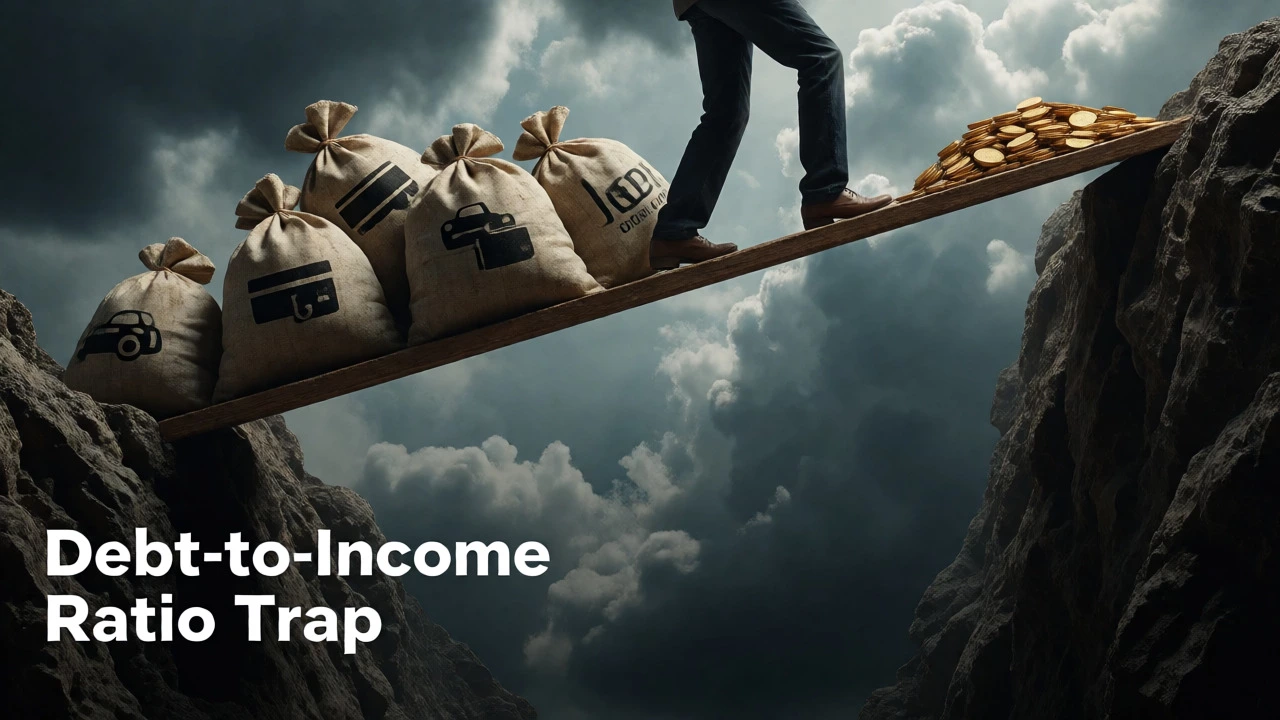
This is where most applicants stumble. You might have $500,000 in equity, but if your monthly income doesn’t support the new repayments plus your existing bills, the deal is dead. This metric is called the Debt-to-Income (DTI) ratio.
Lenders calculate this by adding up all your minimum monthly debt repayments (credit cards, car loans, other mortgages) and dividing that by your gross monthly income. Ideally, they want this number to stay below 40%. If you’re pushing 50% or higher, you’re considered high-risk.
| DTI Percentage | Risk Level | Approval Likelihood | Notes |
|---|---|---|---|
| < 30% | Low | High | Best rates available; minimal stress testing required. |
| 30% - 40% | Moderate | Medium | Standard approval path; may require proof of savings buffer. |
| 40% - 50% | High | Low | Requires strong compensating factors (e.g., large deposit/equity). |
| > 50% | Very High | Very Low | Often declined unless using specialized non-bank lenders. |
Here’s the catch: lenders often use "serviceability buffers." They don’t just look at today’s interest rates. They stress-test your ability to repay assuming interest rates rise by 2.5% to 3%. If your budget breaks under those hypothetical conditions, you fail the test, even if you’re comfortable paying now.
Valuation Woes and Market Volatility
You think your house is worth $1.2 million because your neighbor sold theirs for that amount last month. The bank’s valuer disagrees. Property valuation is an art, not a science, and in fluctuating markets, it’s a contentious one.
Lenders rely on automated valuation models (AVMs) and human valuers. If the market has cooled slightly since your purchase, or if comparable sales (comps) in your suburb are scarce, the bank might value your property conservatively. This directly hits your Loan-to-Value Ratio (LVR).
Most mainstream banks cap home equity loans at 80% LVR. That means if your house is valued at $1 million, and you owe $600,000 on your current mortgage, you only have $200,000 in accessible equity ($800k max borrowable minus $600k owed). If the valuer comes back at $950,000, your accessible equity drops to $160,000. Suddenly, the renovation budget shrinks by $40,000.
In Sydney, where we see distinct micro-markets, this is common. A terrace in Surry Hills might hold value differently than a detached house in Penrith. Lenders know this and apply location-specific discounts to valuations to protect their downside.
Income Verification Nightmares
If you’re a salaried employee with PAYG slips, you’re lucky. Your income is easy to verify. But if you’re self-employed, a contractor, or a small business owner, you enter a labyrinth of documentation hell.
Lenders typically require two years of tax returns, Business Activity Statements (BAS), and profit-and-loss statements. They don’t care about your "projected" income or your best year ever. They average your taxable income over two years. Did you write off expenses aggressively to lower your tax bill? Congratulations, you just lowered your borrowing power.
Many self-employed people struggle here because they optimize for tax efficiency rather than loan eligibility. To get approved, you might need to show higher declared income, which could mean paying more tax in future years-a trade-off few anticipate until it’s too late.
Fees and Hidden Costs Kill the Deal
Even if you get approved, the cost structure can make the loan unattractive. Home equity loans aren’t free. You’re facing establishment fees, valuation fees, legal costs, and potentially ongoing account maintenance fees.
Consider the break-even point. If you’re borrowing $50,000 for six months to bridge a gap, and the fees total $1,500, that’s a 3% immediate cost. Add the interest, and the effective annual percentage rate (APR) skyrockets. Many applicants realize mid-process that the convenience isn’t worth the price tag compared to a short-term personal loan or a line of credit.
How to Improve Your Odds
Don’t let these hurdles discourage you entirely. Thousands of Australians access equity every day. The key is preparation.
- Clean Up Your Credit: Check your report six months before applying. Dispute errors. Pay down small balances to lower utilization.
- Reduce Existing Debt: Paying off a credit card or closing an unused line of credit can instantly improve your DTI ratio.
- Prepare Documentation Early: Gather two years of tax returns and BAS statements. Have payslips ready. Don’t wait for the bank to ask.
- Get a Pre-Valuation: Ask a local real estate agent for a formal appraisal. If it’s significantly lower than expected, factor that into your borrowing plan.
- Compare Non-Bank Lenders: Sometimes, smaller lenders offer better terms for complex situations, though always read the fine print on exit fees.
Getting a home equity loan is hard because it forces you to confront the reality of your financial health. It’s not just about the asset; it’s about the person holding the title. Once you understand the mechanics-credit, DTI, valuation, and income verification-you can navigate the process with confidence rather than frustration.
Can I get a home equity loan with bad credit?
Yes, but it is harder and more expensive. Mainstream banks usually reject applicants with scores below 600 or recent defaults. However, specialist non-bank lenders cater to this demographic. They focus more on the equity position than the credit score. Be prepared for higher interest rates (often 2-4% above prime) and stricter loan caps, such as a maximum 70% Loan-to-Value Ratio.
How does being self-employed affect my application?
Self-employed borrowers face stricter scrutiny. Lenders typically require two years of complete tax returns and Business Activity Statements. They assess your average net taxable income, not your gross revenue or bank deposits. Aggressive tax minimization strategies can inadvertently reduce your borrowing power because they lower your declared taxable income, making you appear less capable of servicing debt.
What is the maximum Loan-to-Value Ratio (LVR) allowed?
Most major Australian banks allow a maximum LVR of 80% for home equity loans. This means you must retain at least 20% equity in the property. Some premium products or non-bank lenders may offer up to 85% or 90%, but this usually attracts Lenders Mortgage Insurance (LMI) or higher interest rates due to increased risk. Always confirm the specific LVR cap with your chosen lender.
Why did the bank value my home lower than I expected?
Bank valuations are conservative risk assessments, not market appraisals. Valuers look at recent comparable sales within a specific radius and timeframe. If sales are sparse or the market has dipped slightly, they will discount the value to ensure they can recover funds quickly if forced to sell. Additionally, unique features or lack of direct comparables can lead to lower valuations. You can challenge the valuation, but success depends on providing concrete evidence of higher recent sales nearby.
Are home equity loans better than personal loans?
It depends on the amount and term. Home equity loans generally offer lower interest rates because they are secured by property. For larger amounts (over $50,000) or longer terms (over 5 years), they are usually cheaper. However, they come with higher setup fees, legal costs, and slower approval times. For small, short-term needs, an unsecured personal loan might be faster and cheaper overall despite the higher interest rate.